Signed into law
Disaster Related Extension of Deadlines Act
This act requires the Internal Revenue Service (IRS) to treat the postponement of the federal tax return deadline due to a federally declared disaster or certain other events as an extension of such deadline for purposes of calculating the limit on a tax refund. The act also provides that the IRS’s deadline for sending certain notices includes such postponement.
- Measure
- H.R. 1491 · 119th Congress
- Latest action
- December 26, 2025
- Policy changes
- 4
- Source
- CRS summary (Public Law) · Congress.gov
Became Public Law No: 119-64.
Who wrote it
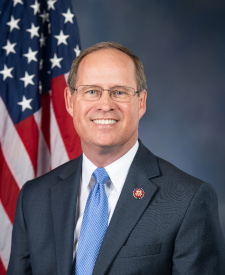
Sponsor
Rep. Gregory F. Murphy (R-NC-3)Joined by 2 cosponsors, 1 of them from the day it was introduced. Introduced February 21, 2025.
All 2 cosponsors
- Rep. Jimmy Panetta (D-CA-19) · original
- Rep. Tim Moore (R-NC-14)
How Congress voted
House · April 1, 2025
Passed/agreed to in House: On motion to suspend the rules and pass the bill, as amended Agreed to by the Yeas and Nays: (2/3 required): 423 - 0 (Roll no. 88).
423 yea · 0 nay · 8 other · Republicans 212–0 · Democrats 211–0 · Official record
Your delegation
Choose your state to see how your senators and representatives wrote, voted on, and spoke about this bill.
In their own words
What members have said about this bill, quoted exactly and linked to the source.
We haven’t found public statements from members about this bill yet.
What it changes — and your vote
One person, one vote · Anyone may read. To vote, verify your identity once with a government-issued ID — we keep no copy of it. Verify to vote
Provision 1
Under current law, a tax refund claim must be filed within three years of the date that the federal tax return is filed.
(Some exceptions apply.) The tax refund amount generally is limited to federal taxes paid within the three years preceding the tax refund claim plus any extension of the federal tax return deadline (known as the lookback period). Under the law in effect prior to this act, the postponement of the federal tax return deadline is not an extension for purposes of the lookback period. Thus, under prior law, certain tax payments (e.g., amounts withheld from a paycheck for federal taxes) made before the federal tax return is filed may be outside the lookback period and non-refundable.
No verified votes yet
Provision 2
Under the act, a federal tax return deadline postponed due to a federally declared disaster or certain other events must be treated as an extension of such deadline for purposes of the lookback period.
No verified votes yet
Provision 3
Further, under current law, the IRS is required to mail a notice and demand for tax payment within 60 days of an assessment but not before the tax payment due date.
No verified votes yet
Provision 4
Provides that the tax payment due date includes the postponement of the tax payment deadline due to a federally declared disaster or certain other events.
No verified votes yet